

What Is Home Healthcare Cover in Health Insurance?
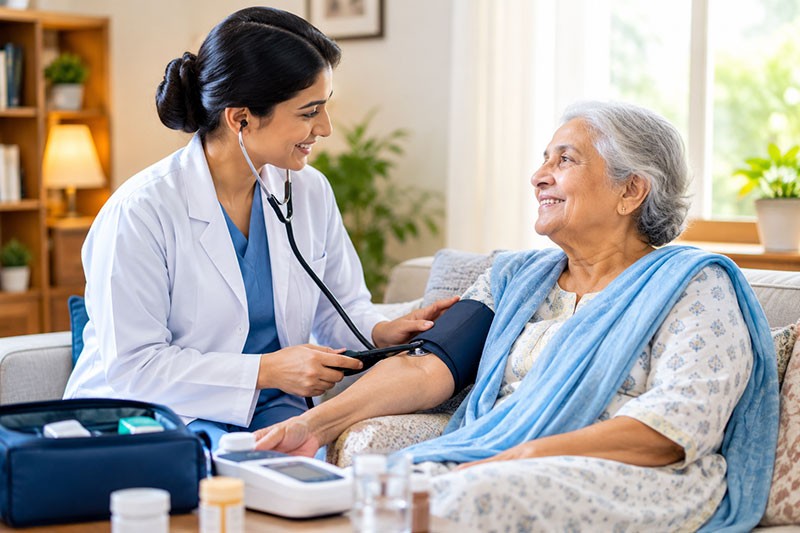
Home healthcare cover allows medical treatments to be received at home when the policy permits it and a doctor recommends home-based care. It is designed for situations where treatment can be managed safely outside a hospital or where home treatment is considered appropriate under the policy.
Depending on the plan, eligible expenses may include medical consultations, nursing support, diagnostic tests and prescribed treatment at home. Coverage remains subject to policy terms, medical advice and claim conditions.
How Does Home Healthcare Cover Work?
Home healthcare is usually available only when it forms part of the policy and the treatment is advised by a medical practitioner. The insurer may require the treatment plan to be approved before care begins when the benefit is offered on a cashless basis.
Some health insurance products include home healthcare within the main cover, while others may structure it differently. The policy wording explains which treatments can be taken at home, whether prior approval is needed and how the claim will be settled.
When Can Treatment at Home Be Considered?
Home treatment may be considered when the patient needs medical care that can be safely delivered outside a hospital. The doctor’s recommendation is important because home healthcare is not the same as choosing to stay at home for convenience.
The insurer may look at whether:
- The treatment has been medically advised.
- The patient needs active medical care at home.
- The treatment falls within the home healthcare benefit.
- The required service is provided through an eligible healthcare provider.
- Any pre-authorisation conditions have been completed.
These conditions can vary, so the policy wording remains the final reference.
What Expenses May Be Included?
The exact scope differs across policies. Depending on the policy, home healthcare may include expenses such as:
|
Expense |
How It May Apply |
|
Doctor Consultation |
Medical visits or supervision required at home |
|
Nursing Care |
Professional nursing support during treatment |
|
Diagnostic Tests |
Tests required as part of the approved treatment plan |
|
Medicines |
Prescribed medicines connected with covered home treatment |
|
Treatment Services |
Medical procedures or therapy permitted under the benefit |
How Is Home Healthcare Different from Domiciliary Hospitalisation?
The two terms may sound similar, but policies can treat them as separate benefits. Home healthcare generally refers to doctor-advised treatment delivered at home under the conditions stated in the policy. Domiciliary hospitalisation usually applies when treatment that would normally require hospital admission is provided at home because the patient cannot be moved safely or suitable hospital accommodation is unavailable.
The eligibility rules, claim process and covered expenses can therefore differ. Understanding this distinction helps avoid assuming that every form of home treatment falls under the same benefit.
Is Home Healthcare Always Cashless?
Not necessarily. Some policies may offer home healthcare through an approved or network service provider on a cashless basis. In that case, the insurer may coordinate with the service provider after pre-authorisation and settle eligible expenses directly.
Other policies may follow a different settlement process. Before treatment starts, confirm whether the benefit is cashless, reimbursement-based, or available only through specific providers.
What Records May Be Needed for a Claim?
Home treatment still needs medical documentation. Insurers may ask for records that show why the treatment was required and what care was provided.
Useful documents can include:
- The doctor’s written recommendation.
- The treatment or care plan.
- Prescriptions and diagnostic reports.
- Bills or invoices, where applicable.
- Records of treatment provided at home.
- Any pre-authorisation or claim documents requested by the insurer.
Keeping these records organised can make the claim easier to assess.
What Should You Understand before Using the Benefit?
Home healthcare cover is useful only when the treatment falls within the policy conditions. Check whether the illness or procedure is eligible, whether any limit applies and whether the insurer requires an approved provider.
Also note that routine assistance at home, personal caregiving and non-medical support are different from medical home healthcare unless the policy specifically says otherwise.
Final Thoughts
Home healthcare cover can allow eligible medical treatment to be delivered at home when it is medically advised and permitted under the policy. The benefit may include doctor visits, nursing, tests, medicines or other approved services, depending on the plan.
Its scope is different from ordinary home assistance and may also differ from domiciliary hospitalisation. Reading the benefit conditions before treatment begins helps you understand how the cover can be used.
Support Our Journalism
We cannot do without you.. your contribution supports unbiased journalism
IBNS is not driven by any ism- not wokeism, not racism, not skewed secularism, not hyper right-wing or left liberal ideals, nor by any hardline religious beliefs or hyper nationalism. We want to serve you good old objective news, as they are. We do not judge or preach. We let people decide for themselves. We only try to present factual and well-sourced news.
Support objective journalism for a small contribution.


